We are now officially into the fourth quarter of the calendar year, and on the proverbial home stretch. Here’s what the new vehicle market did in September.
Reported new vehicle deliveries in September were 108,778 units, up 1.8% over the same month last year. Year-to-date deliveries meanwhile were 957,697 units, up 2.0% YTD. This means the market is on track to break the all-time record for a third successive year, and get close to 1.3 million.
Given the doom and gloom you hear about the economy, this is quite remarkable.
That being said, every brand is discounting and the average invoice-level price cut is around 9% (and nearly 11% via Manheim Australia Vehicle Replacement services). Even cars like the Toyota HiLux and Ford Ranger are being discounted by thousands of dollars right now…
This is being driven by a degree of oversupply but also the avalanche of Chinese brands changing the game.
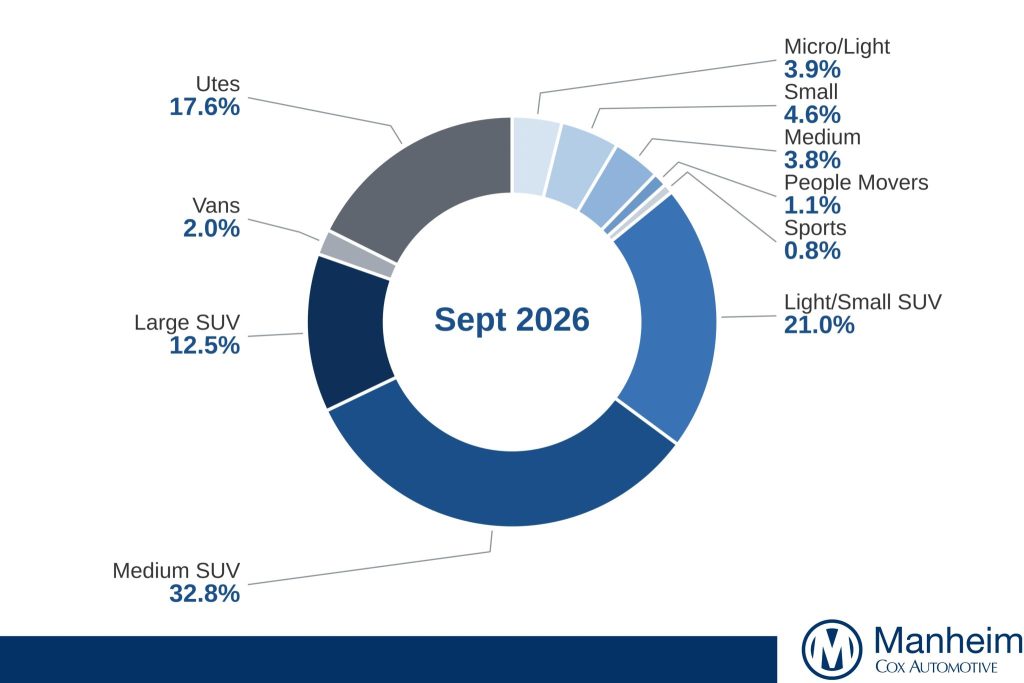
- 64% of deliveries last month were SUVs, half being Mid Sized ones like the Toyota RAV4, Tesla Model Y etc. Nine of the top 20 models were from this size category, easily Australia’s favourite.
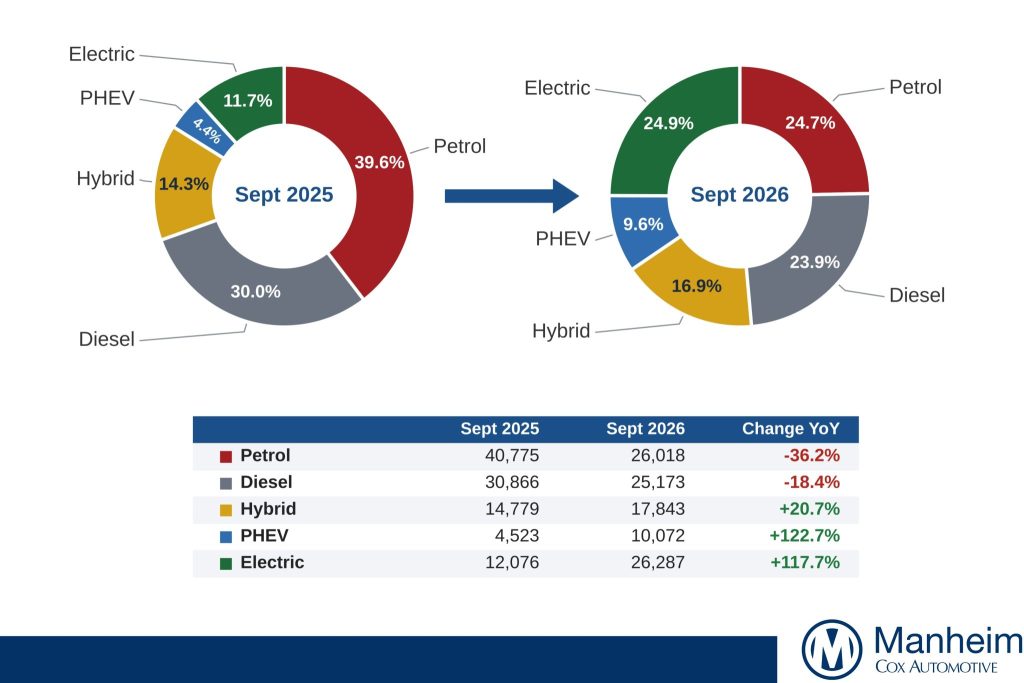
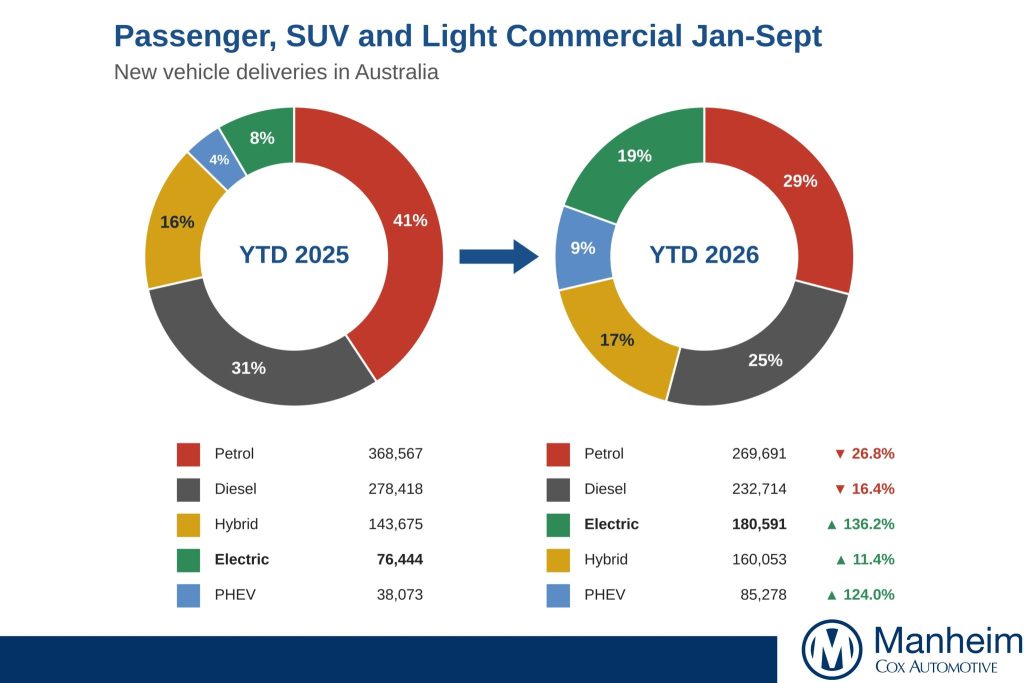
- Nearly 25% of deliveries were BEVs, with sales volumes up 117% YoY and accounting for three of the top 8 models. PHEV market share sat at 9.6%. Diesel and petrol volumes were by consequence down double digits.
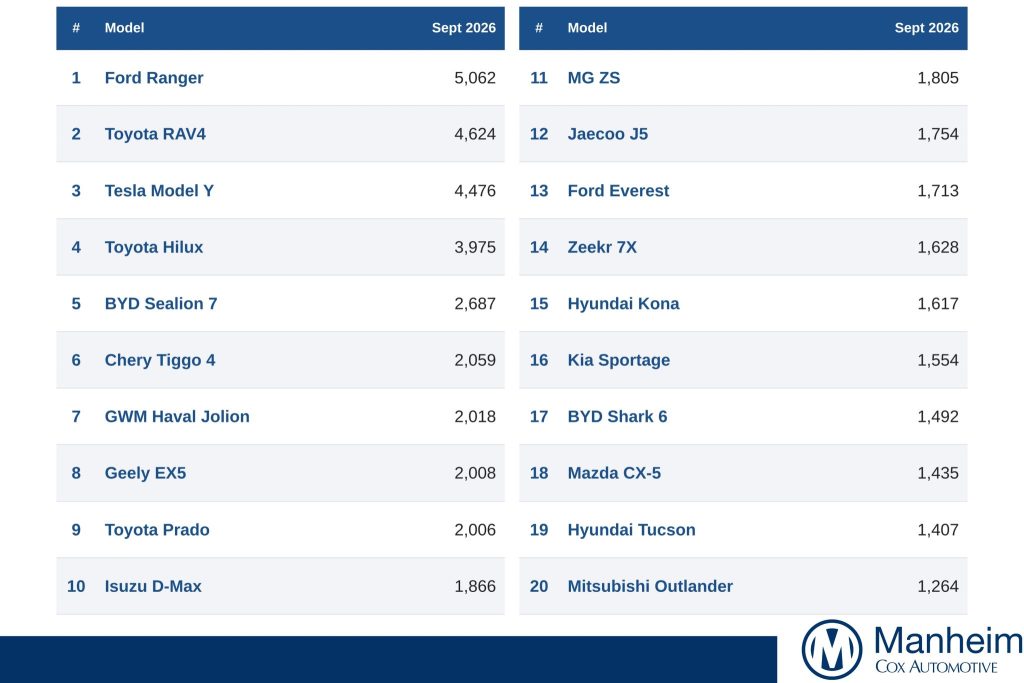
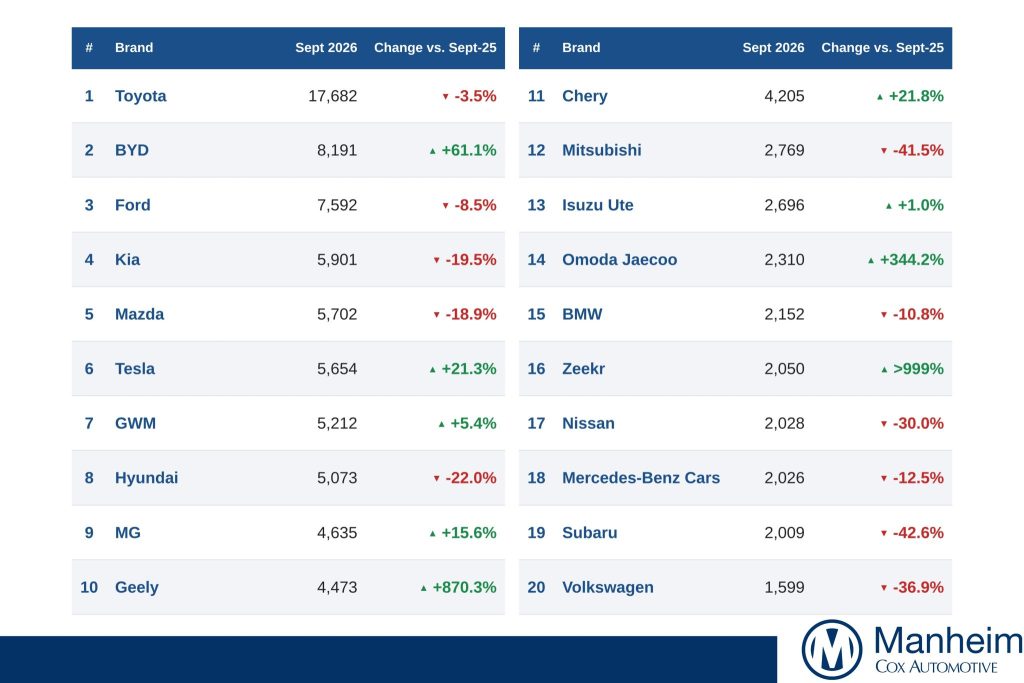
- Toyota was the number one brand but sales were down 3.5% on September 2025 levels. BYD again sat in second, up 61.1%. The Ford Ranger, Toyota RAV4 and Tesla Model Y were top 3 models. See the graphics for the full lists.
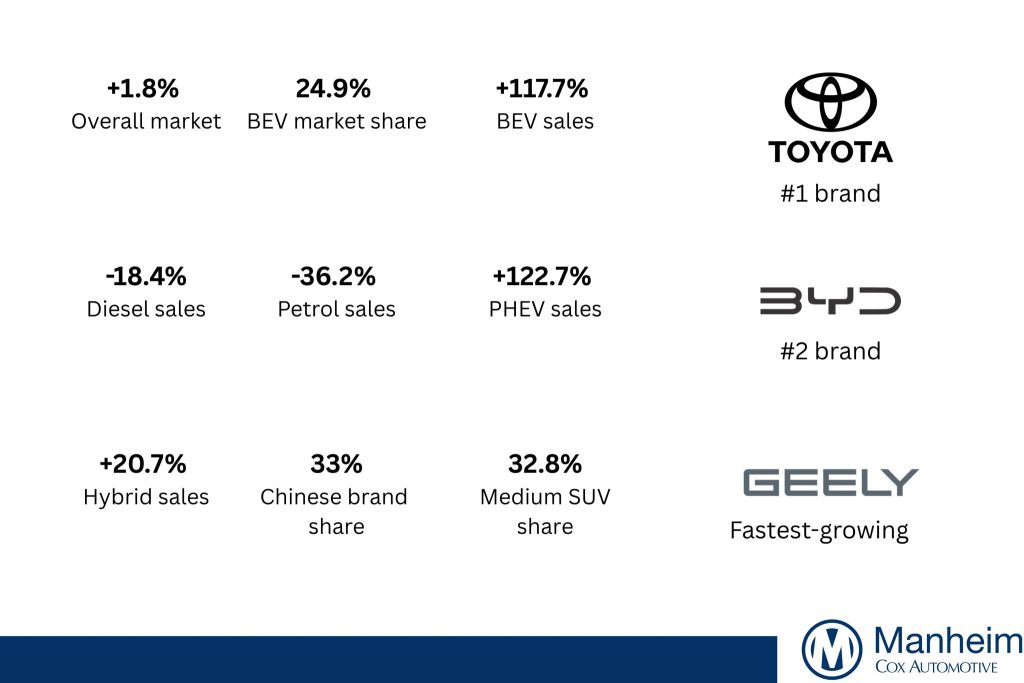
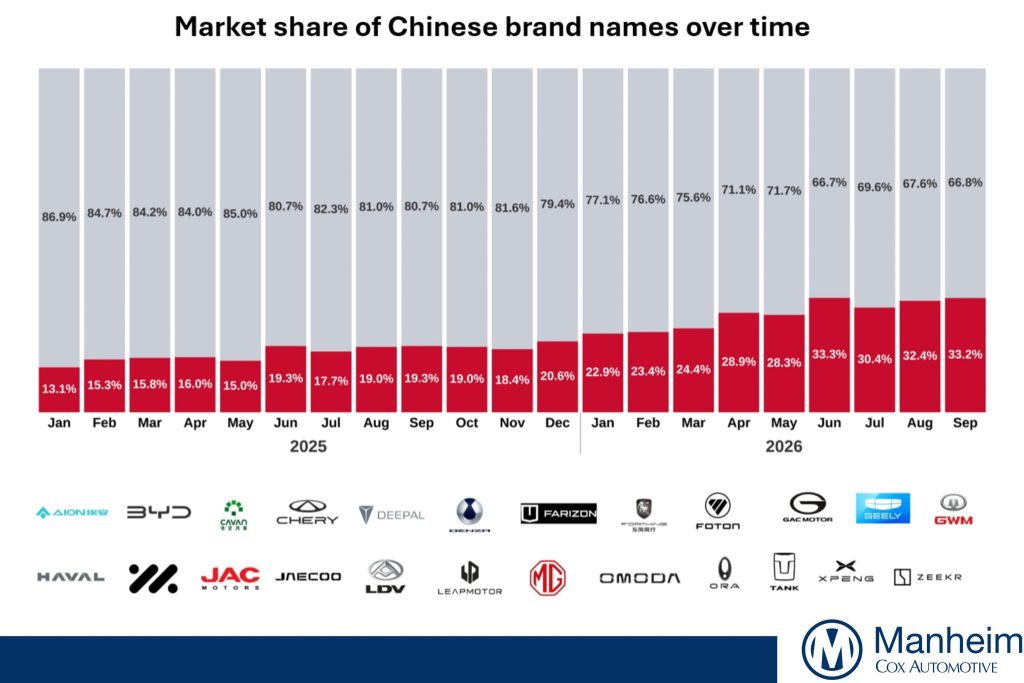
- Chinese brands took 33% market share including 7 of the top 16 brands. Meanwhile Chinese-sourced vehicles including Teslas, Mazdas, Kias etc were 39% of the market, nearly double Japan,and greater than Japan and Thailand combined!
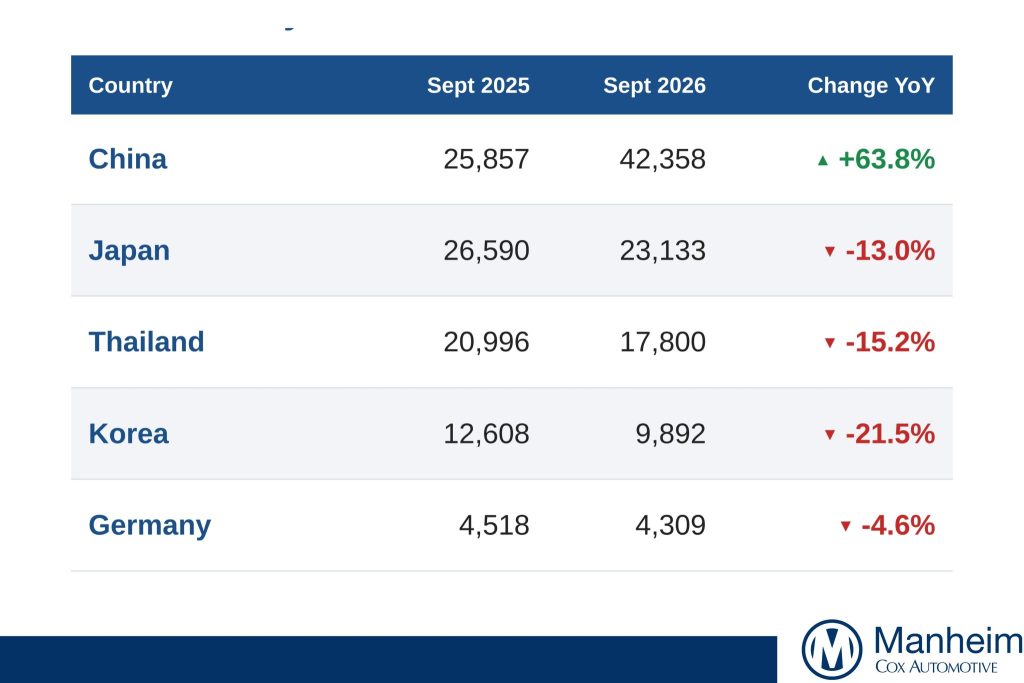
- Deliveries from Japan were down 13%, Thailand was down 15%, Korea was down 21.5% and Germany was down 5%. China was up 64%, meanwhile.
- Toyota, Ford, Kia, Mazda, Hyundai, Mitsubishi, BMW, Nissan, Mercedes-Benz, Subaru and Volkswagen were all in the red. Whereas BYD, Tesla, GWM, MG, Geely, Chery, Isuzu Ute, Omoda Jaecoo, Zeekr all posted growth. That’s the top 20 brands.
- Sales of 4×4 Utes were down 13%, driven by diesel costs. Some 10.6% of all LCVs sold were BEV or PHEV, with electric vans up around 6x YoY.
- Private and lease sales were up 3.6% YoY and business sales down 0.1%. Government sales down 9.7%, which will naturally impact what we see in the lanes…